All Categories
Featured

Smart Wealth Strategies with Life Insurance
An HMO Medicare Benefit plan provides a network (referred to as an "HMO network") of healthcare providers and healthcare facilities to its clients. It's required for a client to select a medical care physician to manage their health care and provide recommendations to any service providers that are not in the strategy's network, other than in case of an emergency.
The ease of having a primary care doctor to collaborate and manage the care offered. A client can only see suppliers within the plan's network unless they have a recommendation for an outside expert, or it's an emergency circumstance.
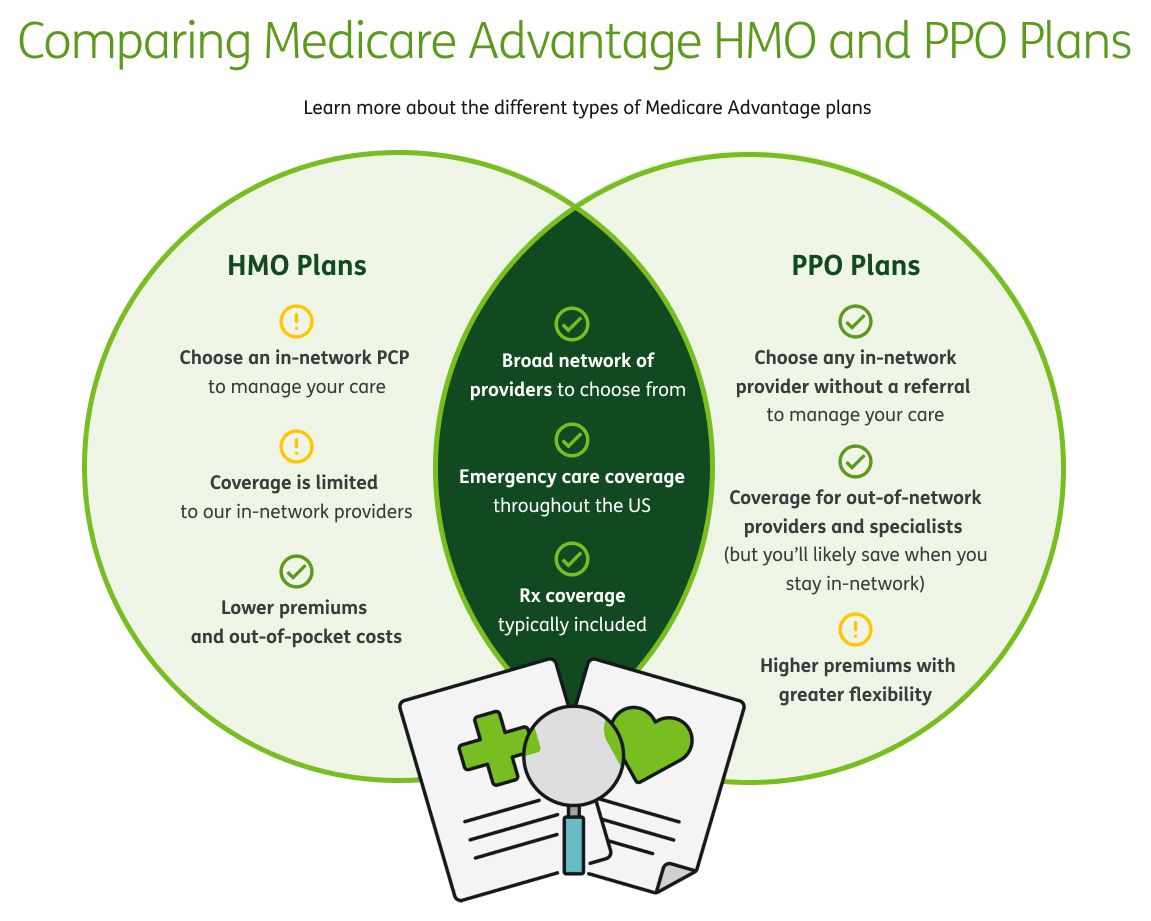
Unlike an HMO plan, a PPO Medicare Benefit plan enables for more versatility when seeing out-of-network companies. It's not needed to have a recommendation to see an out-of-network specialist although it may be more costly and take extra time to get insurance protection given that a client should file a claim for coverage each time they see an out-of-network service provider.
The patient has more versatility with which suppliers they pick to see, whether they're within the strategy's network or out-of-network. Most times, there is no requirement for a referral if a client cares to see an out-of-network professional. Greater monthly premium. More than likely, higher month-to-month premiums. The patient is responsible for handling their healthcare instead of a medical care service provider.
An EPO insurance coverage strategy, or an 'Special Company Company' insurance coverage plan, is often called a plan that is "positioned between an HMO and PPO." This is because, like a PPO plan, an EPO does not need a client to remain in-network for care significance, no recommendations or emergency situations are essential for seeing an out-of-network service provider.
Why Whole Life Protects Family Security
Although this strategy is less widely known, it often supplies a much larger network than an HMO.A POS insurance plan, or a 'Point of Service' insurance plan, is also known to "blend aspects of HMO and PPO plans." This is because, like an HMO strategy, a POS insurance coverage strategy needs a patient to have a primary care physician that manages their healthcare and offers them referrals to out-of-network specialists or service providers.
, the deductible is at least $1,400 for a specific and $2,800 for a family. In order to combat the high deductible expense, it is suggested that a patient contributes to an HSA/HRA or a 'Health Savings Account'/'Health Reimbursement Plan,' which companies frequently contribute to each year.
Another element to note about this plan is that it protects the patient from "devastating out-of-pocket costs for covered services." What this suggests is that, once a client's "annual out-of-pocket expenses for covered services from in-network providers, consisting of deductibles, copayments, and coinsurance, reaches the predetermined devastating limitation," the insurer will cover all expenses.
HMO and PPO strategies share particular functions. Both use a broad network of service providers to pick from, both deal emergency care coverage throughout the United States, and both usually include protection for prescription drugs. There are some primary differences between HMO and PPO plans. HMO strategies require members to pick an in-network PCP to assist handle their care and provide recommendations.
Low-Cost Life Quotes for Veterans
HMOs will not cover care from an out-of-network supplier. HMOs generally have lower premiums and out-of-pocket costs.
Insurance in Lake Forest CAIt's good to have choices. When it pertains to medical insurance, you have your choice of a number of plan types. 2 popular types you'll frequently see are HMO and PPO. Distinctions between HMO (Health Care Company) and PPO (Preferred Service provider Organization) strategies include network size, capability to see specialists, expenses, and out-of-network protection.
An HMO gives you access to particular physicians and hospitals within its network. A network is comprised of suppliers that have actually consented to lower their rates for plan members and also satisfy quality requirements. Unlike PPO plans, care under an HMO strategy is covered just if you see a company within that HMO's network.

Latest Posts

Why Term Life Protects Future Wealth
Affordable Burial Insurance Coverage
Selecting 2026 Medicare Benefits